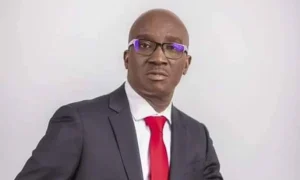

The Group Managing Director of Parthian Financial Services, Mr Oluseye Olusoga, has said Nigeria must sustain ongoing economic reforms, guarantee policy stability and strengthen public institutions in 2027 to translate current economic stabilisation into sustainable growth and competitiveness.
Olusoga said the country could not afford policy reversals or unexpected changes in economic direction, particularly as it approaches the January 16, 2027 presidential and National Assembly elections.
He stated this in his welcome address at the fourth Parthian Economic Discourse, held yesterday in Lagos.
Speaking on the theme, Beyond Stabilisation, Olusoga identified
Speaking on the theme, “Beyond Stabilisation,” Olusoga identified policy stability, strong institutions and continuity of economic reforms as the three critical requirements for Nigeria in 2027.
He warned that election periods often triggered excessive government spending, followed by cuts in public investment after elections, a pattern he said Nigeria must avoid.
According to him, investors are more concerned about the consistency of government policies than the political personalities emerging victorious at elections.
Investors don’t ask, ‘Who will win?’ They ask,
“Investors don’t ask, ‘Who will win?’ They ask, ‘Will the rules still be the same on Monday?’” he said.
Olusoga noted that Nigeria had made significant progress through difficult economic adjustments, including fuel subsidy removal, exchange rate unification, monetary tightening and tax reforms.
He said inflation had declined for five consecutive months to 14.06 per cent in October, its lowest level since 2020, while core inflation fell below 11 per cent and the economy grew by 4.4 per cent in the second quarter.
He cautioned that stabilisation alone was insufficient
However, he cautioned that stabilisation alone was insufficient to deliver prosperity, stressing that the next phase of economic reforms must focus on improving productivity, lowering production costs and making Nigerian businesses competitive globally.
He illustrated the challenges confronting local manufacturers with the example of a factory owner in Agbara who must provide electricity through generators, contend with loan interest rates of between 25 and 30 per cent and spend as much as 26 to 30 per cent of export value transporting goods to the ports.
He added that delays at Apapa port, where goods could remain for up to two months, further undermine the competitiveness of Nigerian businesses.
He also identified the dependence of telecommunications operators
He also identified the dependence of telecommunications operators on diesel-powered generators as evidence of how inadequate infrastructure increases the cost of services to consumers.
According to him, Nigeria must prioritise reliable electricity, efficient ports, functional rail transportation, affordable long-term financing, technology-driven skills development and institutions that guarantee predictable regulations and enforce contracts.
Olusoga cited the country’s electronic payment system as an example of what effective infrastructure, competition and sensible regulation could achieve, noting that the NIBSS Instant Payment platform processed more than N1 quadrillion in transactions in 2024.
He further urged businesses to participate actively
He further urged businesses to participate actively in policy discussions, arguing that engagement with government should be driven by evidence and practical experience rather than political considerations.
“Business cannot sit in the stands and complain about the referee. We have a seat at this table, and we should use it,” he said.
He warned that Nigeria must also build resilience against external shocks, adding that the objective should be an economy whose industries can compete internationally on price and quality without depending on prolonged government protection.